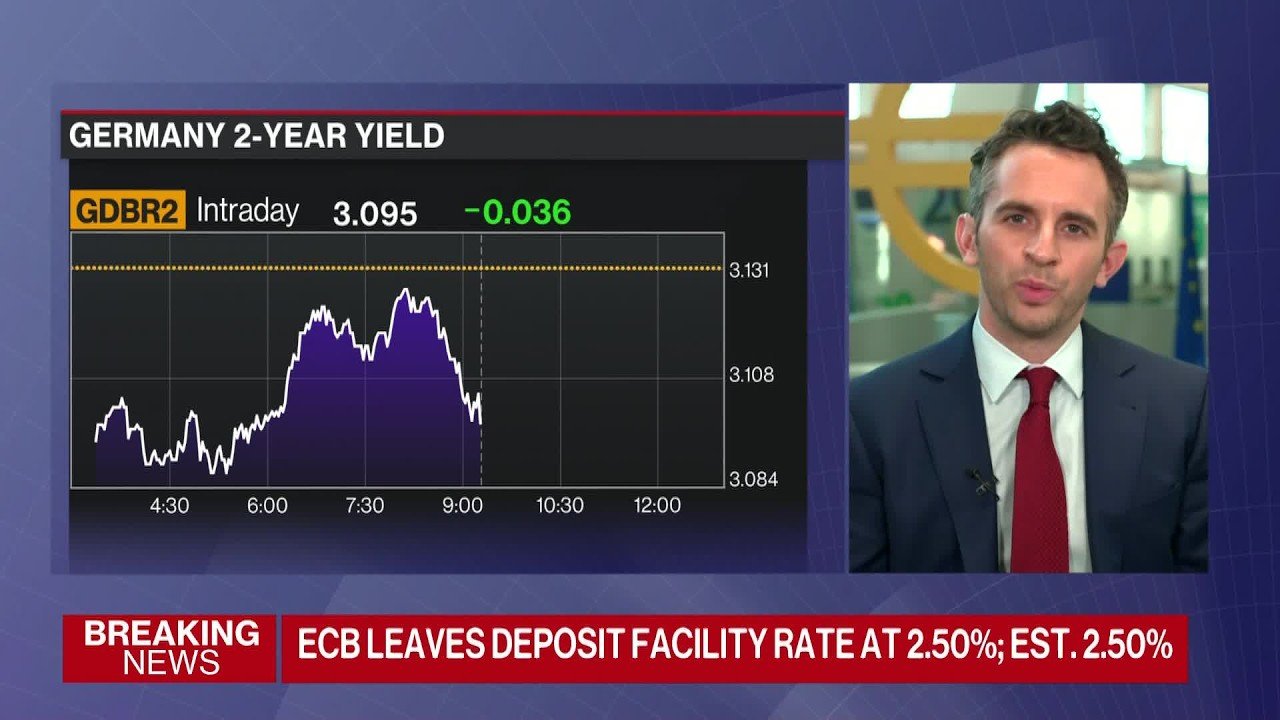
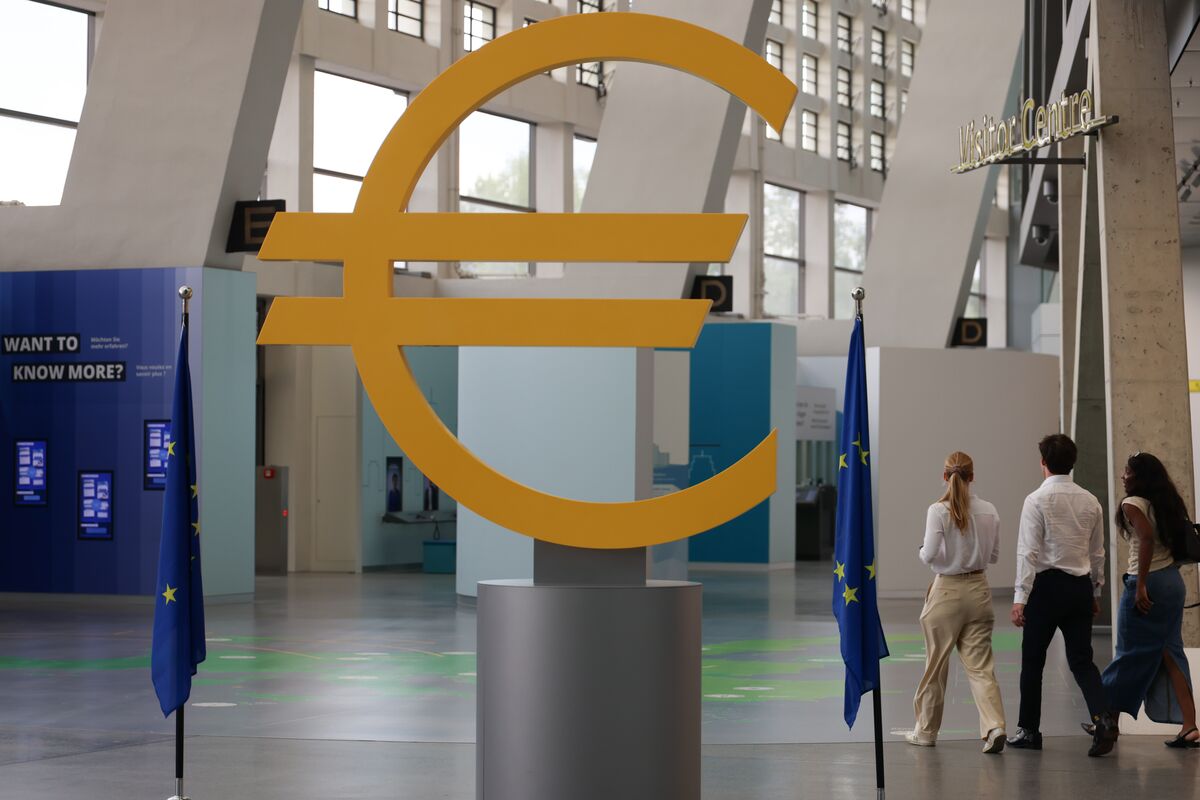

The European Central Bank left interest rates unchanged on October 29, balancing an energy-driven rise in inflation against higher borrowing costs that threaten to weaken the eurozone economy. The decision came hours after President Christine Lagarde announced she would leave office early next year.
The ECB kept its benchmark deposit rate at 2.50%, following two increases earlier this year. Its main refinancing rate remained at 2.65%, while the marginal lending rate stayed at 2.90%. Policymakers discussed another increase but unanimously agreed to hold, Lagarde told reporters after the meeting.
The pause leaves the central bank confronting competing pressures: energy prices are pushing inflation further above its 2% target, while rising market interest rates are already tightening financial conditions without an additional ECB move. The bank warned that the energy shock was likely to both raise inflation and lower growth.
Energy costs drive inflation higher
Eurozone inflation reached 3.8% in September, up from 3.2% in August and its highest level in three years. Energy inflation reached 18.8%, as the conflict in the Middle East continued to disrupt the economic outlook.
For policymakers, the central question is whether those energy increases will spread more widely through the economy. In its statement, the ECB said underlying inflation had remained broadly stable and wages were not yet showing a material response to the latest shock.
That distinction helped explain the decision to wait. A sustained rise in wages and other prices could make an initial energy shock more persistent—a process policymakers describe as “second-round effects.” Lagarde said the bank was not seeing additional effects beyond those already included in its September projections.
Still, the ECB cautioned that the increasing size and duration of the energy shock raised the risk of broader price pressures. Its assessment was not that the inflation threat had passed, but that the evidence did not yet justify an immediate increase.
Bond markets are already raising borrowing costs
The other major consideration was a sharp increase in long-term financing costs. Lagarde said average 10-year sovereign bond yields had risen by about 35 basis points, or 0.35 percentage points, since the previous meeting. The ECB expects tighter financing conditions to weigh on both inflation and economic activity.
France has been a particular focus of market concern. Its 10-year borrowing costs climbed above 5% in the week before the meeting, reaching levels last seen in 2002, as investors assessed the country’s fiscal and political difficulties. On the day of the decision, the gap between French and German borrowing costs stood at roughly 155 basis points, according to Euronews.
Those market moves complicate the ECB’s task. Higher financing costs can restrain demand, reducing the need for further monetary tightening, but they can also put additional pressure on growth. The bank explicitly acknowledged that financing conditions had tightened since its September meeting.
The ECB reiterated that its Transmission Protection Instrument remained available to counter unwarranted, disorderly market movements that seriously threaten the transmission of monetary policy across the eurozone. It did not announce that it would activate the instrument.
A pause after two rate increases
October’s decision followed two rate increases this year, including a quarter-percentage-point rise in September. The hold therefore represented a pause in tightening, rather than an announced end to the cycle.
The ECB said it would continue to make decisions meeting by meeting, assessing incoming economic data, the inflation outlook, underlying price pressures and how monetary policy was affecting the economy. It explicitly ruled out committing in advance to a particular rate path.
Investors nevertheless continued to anticipate a possible December increase. Money markets priced in approximately a 67% probability of a hike after the announcement, according to LSEG data reported by CNBC. Deutsche Bank economist Mark Wall forecast one further increase, taking the deposit rate to 2.75%, while UBS economist Dean Turner described the decision as a “hawkish pause.” Those assessments were market expectations, not ECB commitments.
Updated growth and inflation forecasts in December will give policymakers another opportunity to judge whether higher energy costs are becoming embedded in the broader economy.
Lagarde’s departure adds leadership uncertainty
The policy decision coincided with Lagarde’s announcement that she would step down on February 7, 2027, ahead of the scheduled end of her eight-year term in October. Her departure opens a succession process while the central bank is managing renewed inflation pressures and instability in European bond markets.
The reason for the timing requires a distinction between the official announcement and subsequent reporting. Euronews reported that the ECB gave no reason for the early departure, while news reports linked it to allowing European leaders to choose a successor before France’s spring presidential election. AFP likewise reported that the timing would allow a selection before the vote, amid concern that a far-right victory could complicate negotiations.
Former Spanish central bank governor Pablo Hernández de Cos and former Dutch central bank chief Klaas Knot were identified by Euronews as leading contenders. No successor was announced in the reporting accompanying the October decision.
Balance-sheet reduction continues
The ECB also left another part of its policy stance unchanged: the gradual reduction of its bond holdings. Portfolios accumulated through the Asset Purchase Programme and Pandemic Emergency Purchase Programme continue to shrink because the Eurosystem is no longer reinvesting principal payments from maturing securities.
For now, policymakers have chosen to observe how the energy shock and tighter financing conditions develop before changing rates again. The next decision will turn on whether inflation remains predominantly energy-driven or spreads more persistently into wages and other prices—and how much economic activity weakens in the meantime.