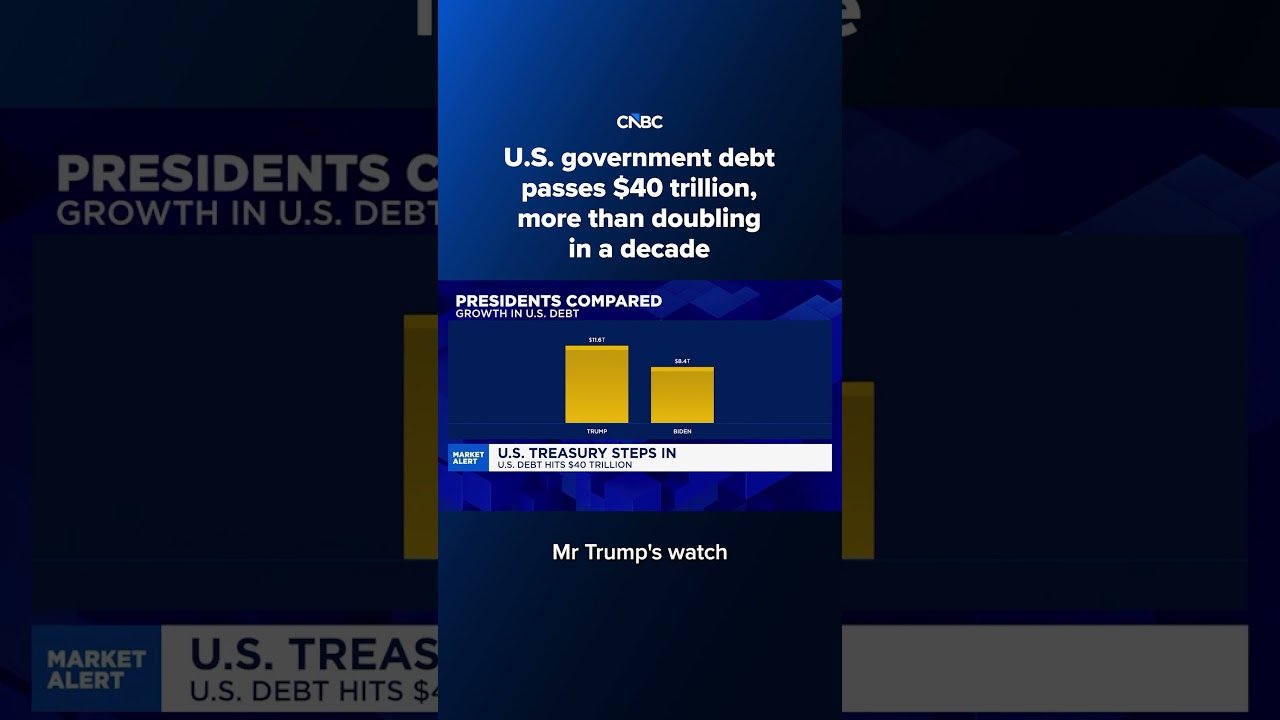


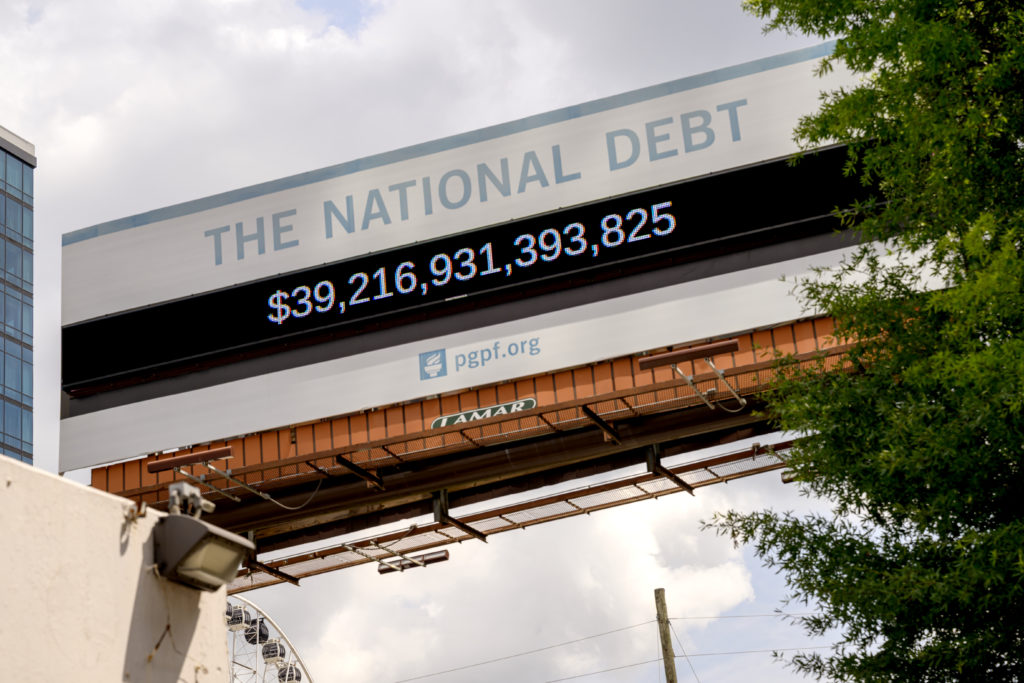

The United States crossed a stark fiscal threshold this week: total federal debt topped $40trillion for the first time in history, reaching about $40.05trillion on August 18, 2026, according to Treasury Department data. The odometer rolled over just over four years after the $30trillion mark in early 2022, underscoring an acceleration that has doubled the nation’s debt in under a decade.
Treasury’s daily “Debt to the Penny” report shows total public debt outstanding at $40.047trillion, composed of roughly $32.27trillion held by the public and about $7.78trillion in intragovernmental holdings.
The pace has quickened markedly: the most recent trillion took about five months to add, and the last $9trillion accumulated in roughly four years. Over the past 12 months alone, debt rose by about $2.9trillion, or 7.8%.
Why it’s growing so fast
Three forces dominate the trajectory:
- Structural spending: Mandatory programs such as Social Security and Medicare, alongside elevated defense and other discretionary outlays, keep baseline expenditures high.
- Pandemic-era baseline: Large stimulus and relief packages permanently lifted the federal spending floor, with borrowing needs remaining elevated even after emergency programs ended.
- Interest compounding: Higher debt levels and elevated long‑term rates have pushed annual interest costs sharply higher. The Congressional Budget Office reported net interest of about $963billion from October 2025 through July 2026—roughly $3.2billion a day—up 14% from the prior year.
Debt burden and the path ahead
The debt-to-GDP ratio is now on a rising path that budget watchdogs describe as unsustainable without policy changes. The Congressional Budget Office projects the ratio could reach 120% within a decade and 175% over 30 years. The Peterson Foundation estimates that, absent spending or tax reforms, the national debt could hit $50trillion within six years.
What this means for investors
Crossing $40trillion does not trigger any automatic market event or statutory change, but the macro backdrop it reflects carries portfolio implications.
- Crowding-out risk: As the Treasury issues more securities to fund deficits, capital is drawn toward government paper, potentially raising the cost of private investment and weighing on long‑term productivity.
- Inflation and rates: Persistent large deficits can embed structural inflation pressures, helping keep consumer borrowing costs—mortgages, credit cards, auto loans—elevated for longer.
- Guardrails for portfolios: In a high‑debt, higher‑rate environment, overreliance on cash or nominal bonds can expose real returns to erosion. Diversification into inflation‑resilient assets—global equities, real assets such as real estate and infrastructure, and hard commodities—is a common hedge against fiscal instability and purchasing‑power risk.
The next flashpoint: The debt ceiling
The current statutory debt limit stands at $41.1 trillion. With debt already at $40.05 trillion, Congress will likely face a ceiling debate in the coming months to avoid a technical default once the limit is reached. That political timeline, rather than the $40 trillion round number itself, is the nearer‑term catalyst markets will watch.