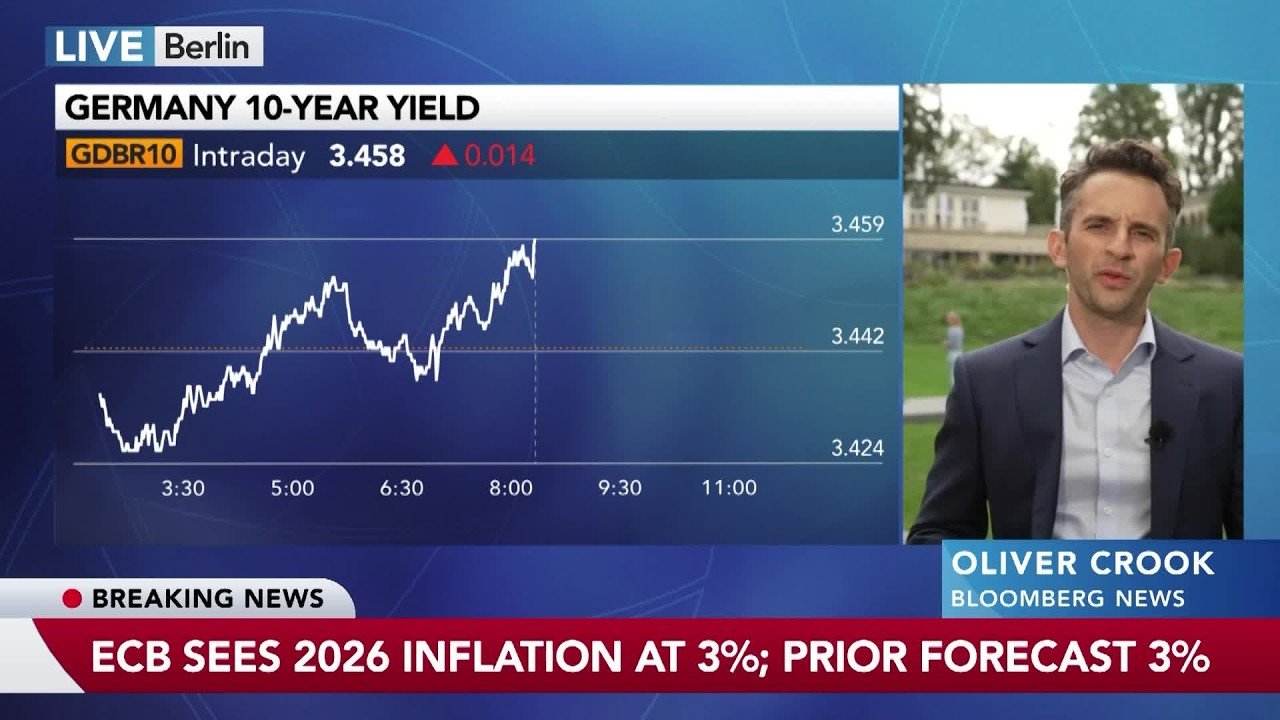
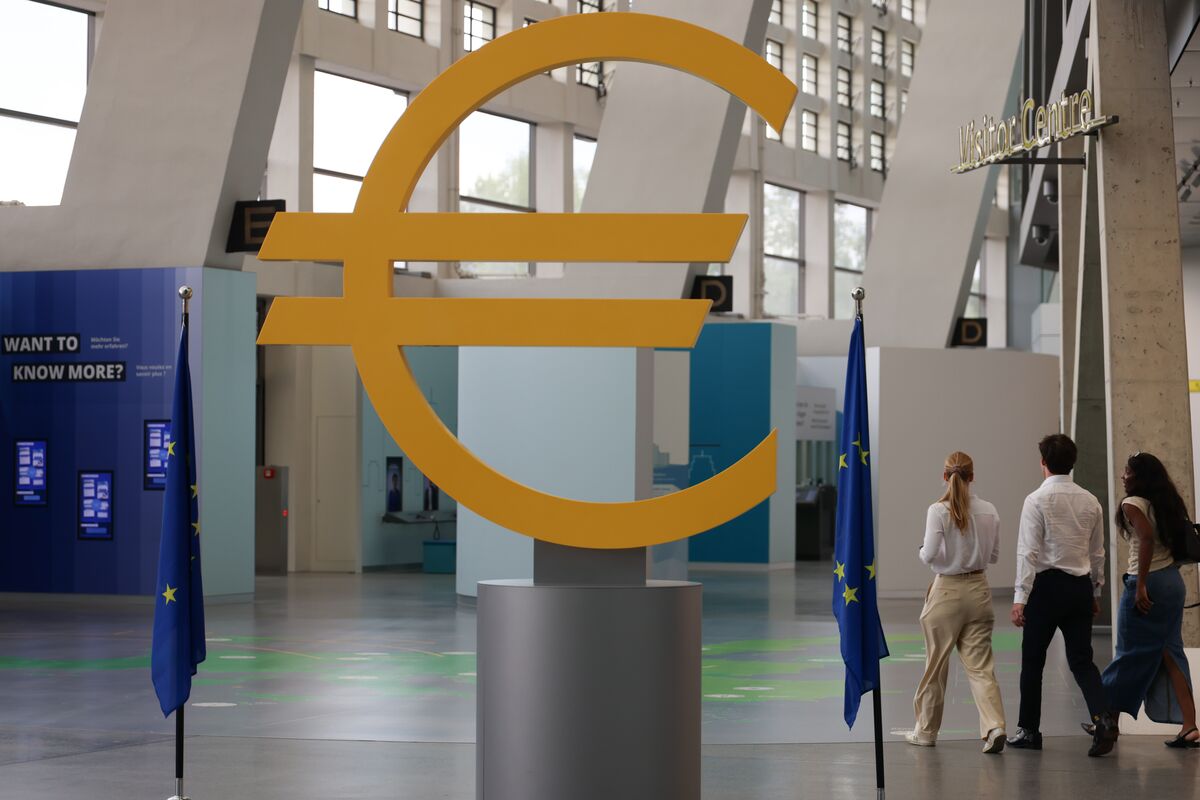


The European Central Bank raised its key interest rates by 25 basis points on September 10, 2026, lifting the deposit facility rate to 2.50% in a unanimous decision aimed at containing energy-driven inflation after oil prices surged past $100 a barrel amid escalating conflict in the Middle East.
ECB President Christine Lagarde called the move a “no-brainer,” warning that price pressures would remain “well above target for an extended period” and that the outlook carried upside risks for inflation and downside risks for growth.
The Governing Council, meeting in Berlin for its annual external session hosted by the Bundesbank, increased all three key rates by a quarter point, with the new levels taking effect on September 16.
- Deposit facility rate: 2.50% (from 2.25%) — the ECB’s main policy benchmark.
- Main refinancing operations rate: 2.65% (from 2.40%).
- Marginal lending facility rate: 2.90% (from 2.65%).
The decision was unanimous, underscoring the Governing Council’s shared view that further tightening was necessary to prevent a temporary energy spike from becoming entrenched in wages and core prices.
Why the hike: an oil-driven inflation shock
Eurozone headline inflation accelerated to 3.3% in August 2026, up from 2.9% in July, driven largely by a 14.3% year-on-year jump in energy prices. Brent crude settled above $101 a barrel on September 9 after Middle East tensions disrupted shipping and raised concerns about flows through the Strait of Hormuz, with prices at times trading above $103. European fuel prices rose in tandem, adding to household and business cost pressures across the bloc.
Lagarde said the conflict in the Middle East “continues to generate inflation pressures,” and that the ECB expects inflation to stay above its 2% target for longer than previously anticipated.
Updated forecasts: higher inflation for longer, but resilient growth
Alongside the rate decision, the ECB released new macroeconomic projections that reflect a slower disinflation path but sturdier near-term activity.
- Inflation (HICP):
- 2026: 3.0% (unchanged from June projections)
- 2027: 2.5% (raised from 2.3%)
- 2028: 2.1% (raised from 2.0%)
Core inflation is seen at 2.5% in 2026, 2.6% in 2027, and 2.3% in 2028.
- Real GDP growth:
- 2026: 0.9% (up from 0.8%)
- 2027: 1.4% (up from 1.2%)
- 2028: 1.5% (unchanged)
The upward revisions to growth point to “greater than expected resilience” across countries and sectors, with Lagarde noting that the pattern of broad-based expansion likely continued into the third quarter despite the energy shock.
Policy stance: at the edge of “neutral,” with more tightening on the table
At 2.50%, the deposit rate now sits at the upper end of the ECB’s estimated neutral range, the level at which policy neither stimulates nor restrains the economy. ECB policymaker and Bundesbank President Joachim Nagel said the bank “might need to raise interest rates further” into mildly restrictive territory if war-fuelled energy prices persist.
While Lagarde emphasized that the ECB is not pre-committing to a path and will remain data-dependent, her language and the upgraded inflation projections have shifted market expectations toward additional tightening.
What markets and banks are pricing in next
Money markets responded by pricing in roughly 60 basis points of additional ECB tightening by April 2027, up from about 51 basis points before the meeting. Several major banks have moved their forecasts forward:
- Barclays, Goldman Sachs, and Citigroup now see another 25bp hike as early as December 2026, with some analysts even flagging the possibility of a move in October if energy prices remain elevated.
- The hawkish tone also weighed on European equities, with shares falling to two-month lows as traders adjusted to the prospect of a more restrictive policy path.
What this means for households and businesses
The rate increase will feed through to borrowing costs across the euro area over the coming months, affecting mortgages, business loans, and credit lines. With inflation projected to stay above target through 2027 and energy markets volatile, the ECB is signaling that it is prepared to keep policy tight enough to ensure inflation returns sustainably to 2%, even if that means accepting slower growth later in the forecast horizon.
For now, the message from Frankfurt—and Berlin—is clear: the energy shock from the Middle East has complicated the disinflation process, and the ECB is willing to move again if needed to prevent second-round effects from taking hold.