The third European Industry Summit in Antwerp ended on February 12, 2026, with industry leaders and political officials warning that Europe needs an emergency industrial policy to avoid a deeper collapse in manufacturing. More than 1,300 executives gathered with policymakers against a backdrop of high energy costs, factory closures and mounting pressure to keep industrial production in Europe.
The summit was framed as a make-or-break moment for the bloc’s economic future, with leaders packaging energy reform, trade policy and financial integration into a political push that will run through June 2026. European Council President António Costa said the EU had begun to embrace Enrico Letta’s vision of moving from an “incomplete single market” to “one market for one Europe” by the end of 2027.
Emergency measures and market reform
A central demand from industry was the adoption of an “emergency industrial policy” in 2026, with business leaders warning that current conditions are no longer sustainable. They pointed to 101 site closures and 75,000 lost jobs in the chemical sector alone as evidence of the scale of the damage.
Among the main proposals discussed was “EU Inc,” also known as the 28th regime, which would create a single legal framework for companies operating across all 27 member states. Leaders also backed “buy European” and “made in Europe” rules, describing them as targeted and proportionate measures to shield strategic sectors from global competition.
European Commission President Ursula von der Leyen said a forthcoming Industrial Accelerator Act would introduce EU content requirements for strategic industries and use public procurement to support demand for European-made clean products.
Energy and investment pressure
Energy costs dominated the debate, especially the gap between industrial electricity prices and gas taxes. Von der Leyen said industrial electricity taxes are currently 15 times higher than those on gas and pledged to work with national governments on reforming energy taxation.
Delegates also discussed the future of the EU carbon market and the post-2030 emissions framework, both of which remain politically sensitive as the bloc tries to balance climate targets with industrial competitiveness.
The Commission also warned that if EU governments fail to agree on the Savings and Investment Union by the end of 2026, it could move ahead with a smaller coalition of willing states. That plan could unlock as much as €470 billion in private investment, and reflects a broader willingness among major capitals to use flexible integration if unanimity proves impossible.
June deadline and two-speed Europe
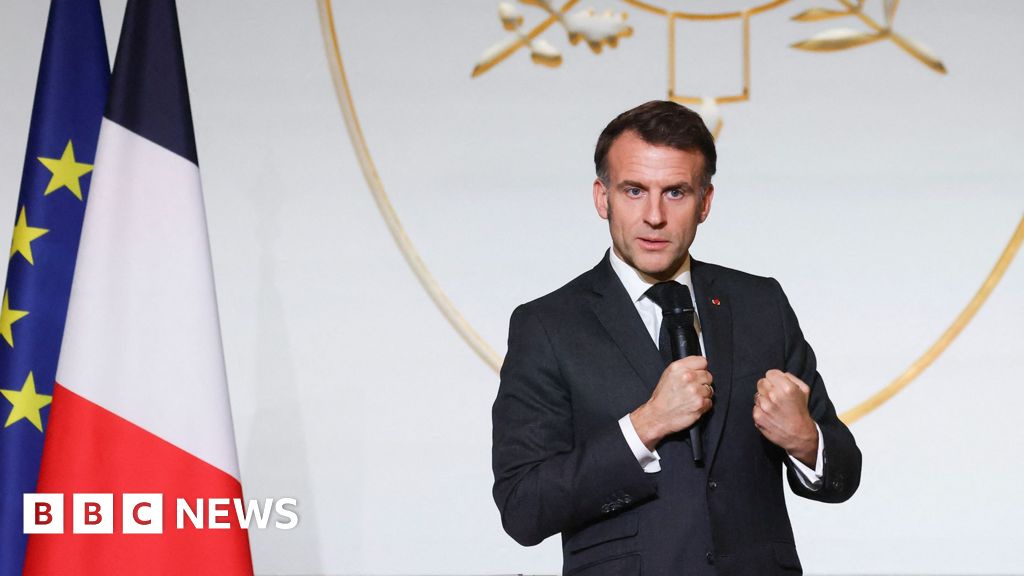
French President Emmanuel Macron has set the June 2026 European Council as the deadline for a broader economic relaunch package. If all 27 member states cannot agree by then, he has said a smaller group could press ahead using the EU’s “enhanced cooperation” mechanism.
The package is expected to focus on completing the Savings and Investment Union, cutting regulatory barriers and delivering concrete steps on energy prices and simplification. Von der Leyen has backed the same timeline, saying she is prepared to consider enhanced cooperation if the “speed of the slowest” continues to block reform.
Eurobonds and trade disputes
Macron also pushed for the relaunch package to include common EU debt, arguing that Europe needs large-scale joint borrowing to finance the huge investment bill facing the bloc. He has said the continent needs as much as €800 billion to €1.2 trillion a year in public and private investment for AI, clean energy, defense and advanced technology, and has argued that Eurobonds are the only realistic way to keep pace with the United States and China.
Germany remains opposed. Chancellor Friedrich Merz said he would not back Eurobonds and described joint borrowing as a last resort, citing German fiscal limits. The divide also surfaced in trade policy, with Macron calling for tariff measures on Chinese imports if global imbalances persist, while Merz argued instead for deregulation, lower red tape and support for the Mercosur trade deal.
European leaders have recast their latest Antwerp gathering as a make-or-break moment for the bloc’s industrial future, wrapping a dense package of energy, trade and financial reforms into a high‑stakes political showdown running to June 2026.