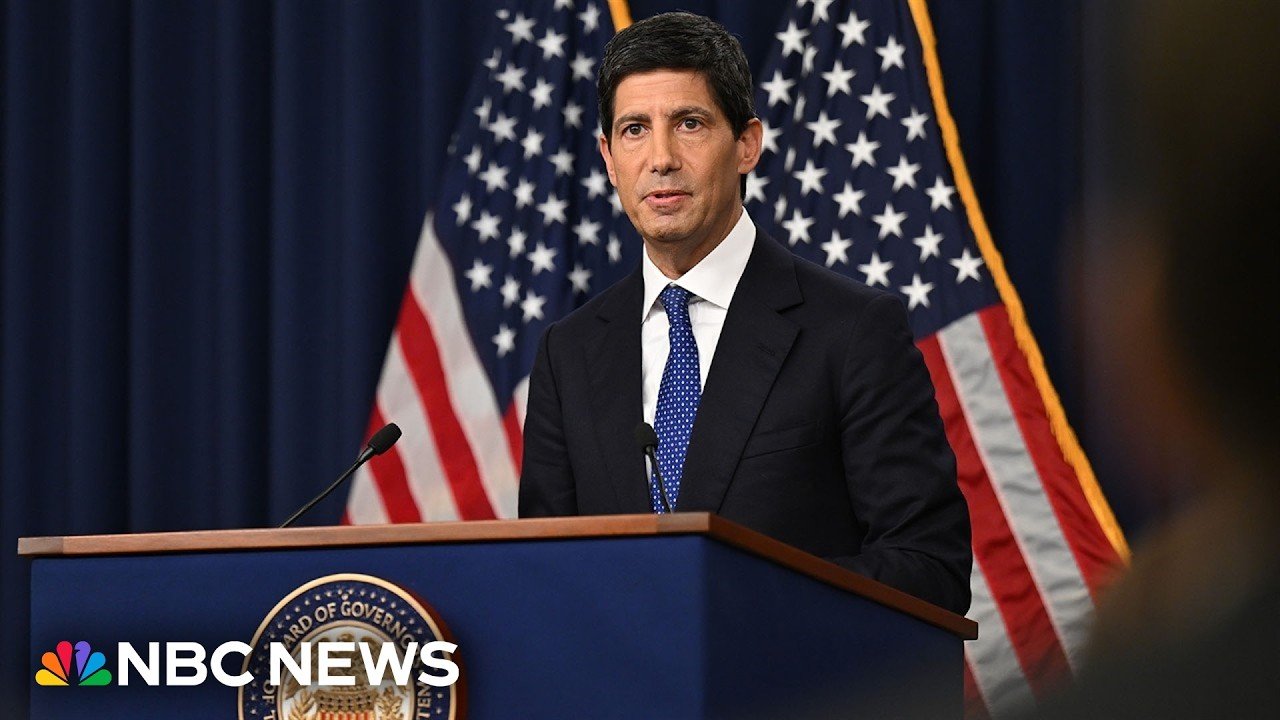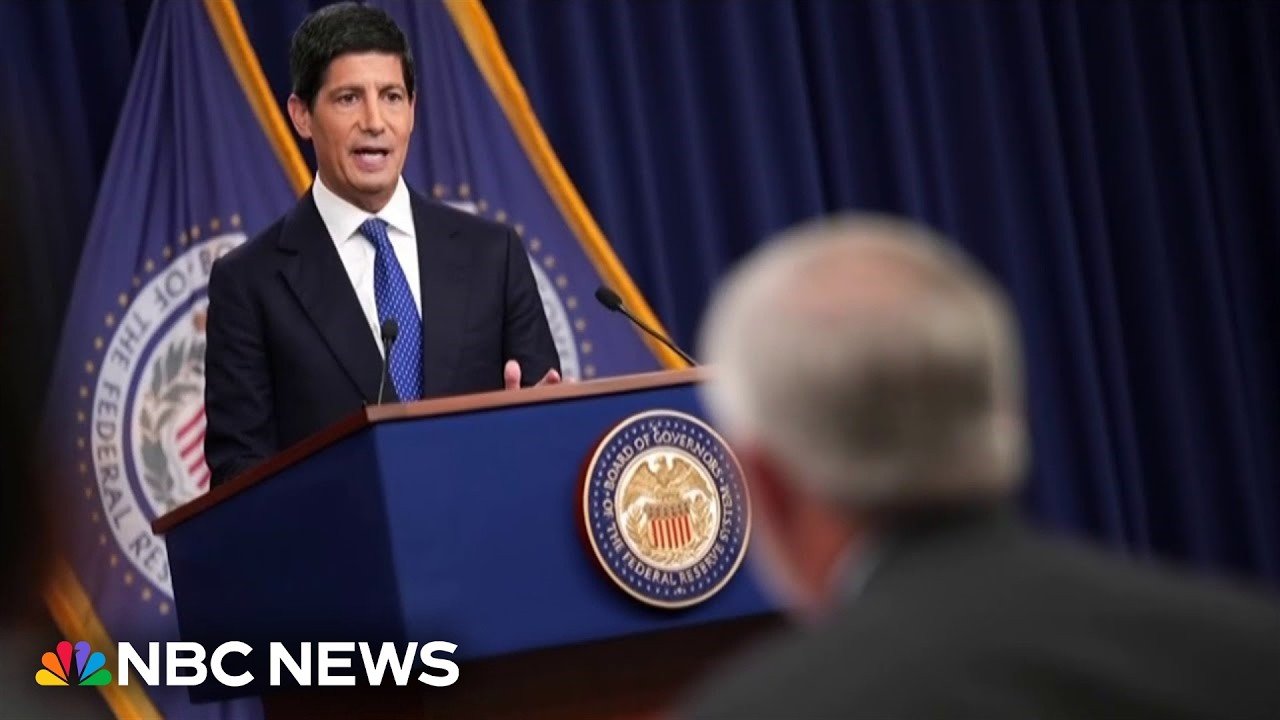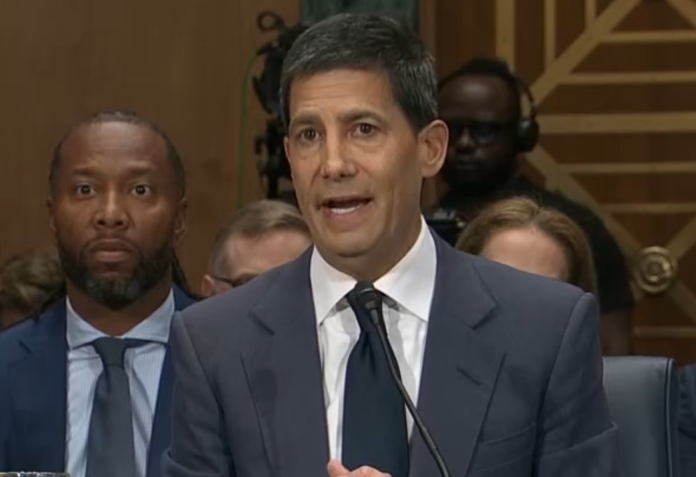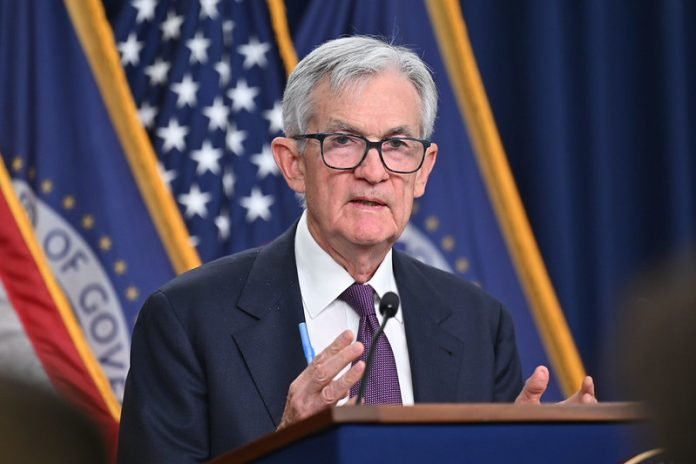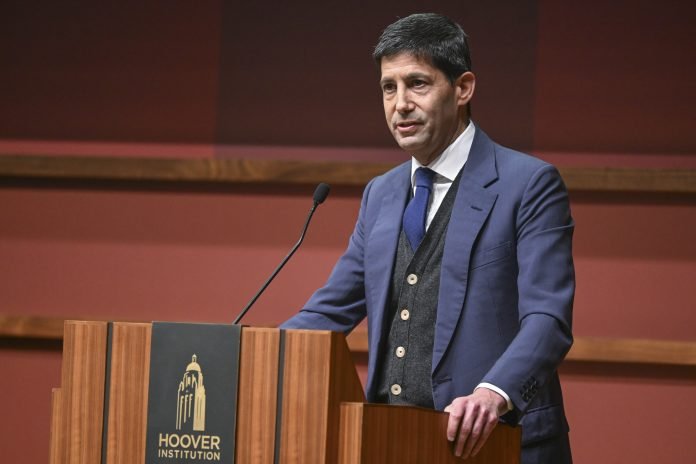


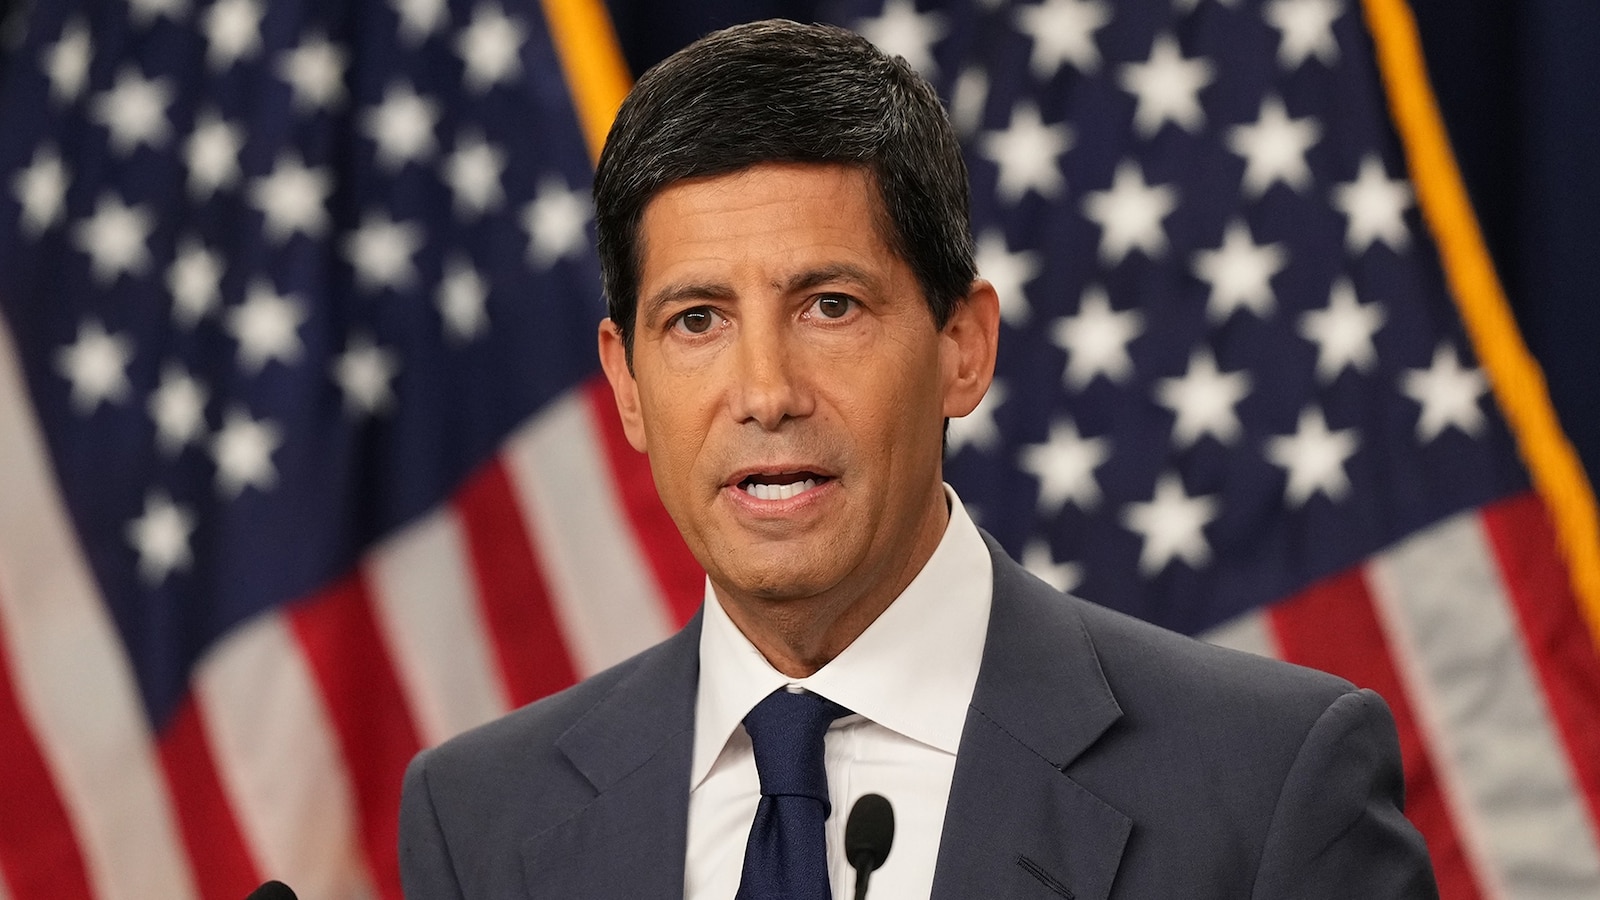




The US central bank pauses after September’s increase, with two officials seeking another hike and Chair Kevin Warsh announcing plans for fewer rate-setting meetings.
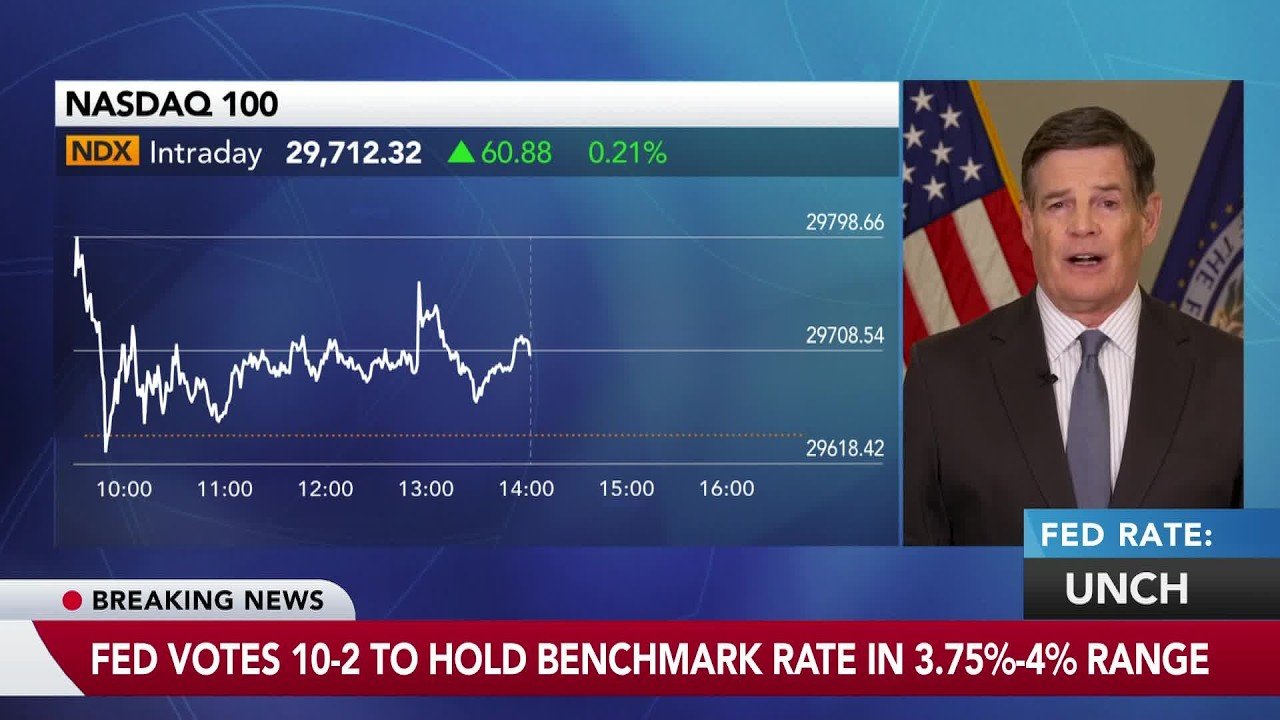
The Federal Reserve held interest rates steady on October 28, opting to assess incoming economic data before raising borrowing costs again as inflation remains elevated and economic growth strengthens.
The Federal Open Market Committee voted 10–2 to maintain its benchmark federal funds target range at 3.75% to 4.00%. Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented, preferring a quarter-percentage-point increase. The decision followed September’s unanimous vote to raise rates by the same amount.
The pause did not signal an end to the Fed’s inflation fight. In its statement, the committee said “the accumulation of more information” would help determine the policy needed to bring inflation back to its 2% target. “The Committee will deliver price stability,” it added.
A stronger economy complicates the inflation fight
The Fed upgraded its assessment of economic activity from a “solid pace” in September to a “strong pace” in October. It described domestic spending as resilient, productivity growth as strong and capital investment as robust, while acknowledging continued uncertainty linked partly to geopolitical developments.
Consumer price inflation reached 3.7% in September, driven by higher energy costs. Wholesale price pressures also intensified: the producer price index rose 6.3% from a year earlier, its steepest annual increase since 2022, according to CNBC’s reporting.
Those figures require an important distinction. The September consumer price index reading was already available when policymakers met, but the September personal consumption expenditures price index — the Fed’s preferred inflation gauge — was scheduled for release on October 29. Economists expected that report to show further inflation pressure; those expectations were not yet confirmed data at the time of the decision.
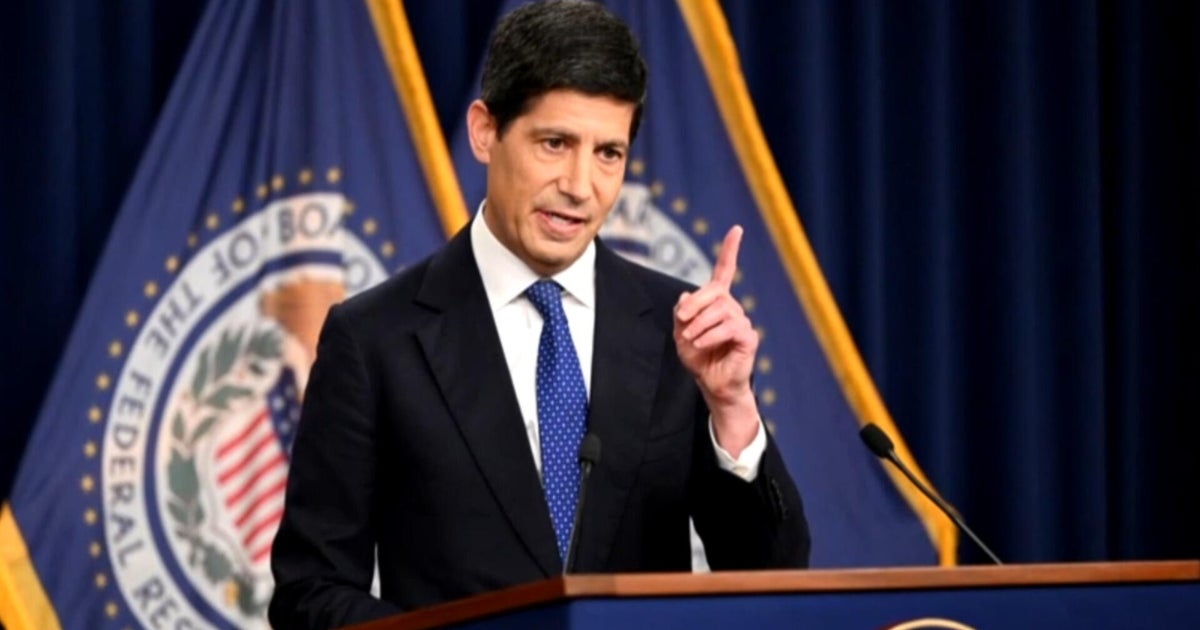
Warsh nevertheless rejected the idea that strong growth necessarily required the Fed to slow the economy sharply. He argued that improvements in productivity could allow faster expansion without generating as much inflation.
The goal, in my view … isn’t to throw sand in the gears of the economy and throw people out of work.
Warsh told reporters.
I don’t think we have to do that.
Low unemployment masks slower hiring
The labor market offered a more mixed picture than the unemployment rate alone suggested. Unemployment stood at 4.2% in September and had remained within a narrow 4.1% to 4.3% range since March, according to the Bureau of Labor Statistics.
But employers added just 29,000 jobs in September, below the 84,000 expected by economists surveyed by Dow Jones. The unemployment rate edged up from 4.1% in August, largely because more people entered the labor force.
That combination — low unemployment but subdued hiring — helps explain the competing pressures facing policymakers. The Fed’s statement said job gains had kept pace with workforce growth, while Warsh said the committee’s discussions focused mainly on the price-stability side of its mandate.
Cook and Hammack’s votes exposed a disagreement over how quickly to act. Their formally recorded position was that rates should rise immediately by a quarter percentage point; the committee statement did not provide individual explanations for their dissents.
AI investment sits at the center of the debate
The artificial intelligence investment boom has become part of the argument over whether economic strength is adding to inflation or expanding the economy’s capacity to grow. Reuters reported that some Fed officials worry demand supported by AI investment and healthy consumer spending is pushing prices higher. Warsh, by contrast, emphasized the potential benefits of stronger productivity.
He also disputed the suggestion that AI-related investment was insulated from monetary policy. Higher rates had affected financial and credit conditions, he said, with investors becoming more selective about where they committed capital.
We have started to see some changes in financial and credit conditions; they have tightened for some businesses and households, much as we would expect.
Warsh said, stopping short of describing financial conditions as broadly tight.
The disagreement is therefore not simply about whether the economy is strong. It is also about how much of that strength reflects improved productive capacity, how much is adding to price pressures and how much restraint September’s rate increase is already delivering.
Warsh rejects election influence
The decision came six days before the November 3 US midterm elections, against a backdrop of President Donald Trump’s repeated demands for lower interest rates. After September’s increase, Trump described Warsh’s policymaking colleagues as “hostile” and “partisan,” Reuters reported.
Warsh said electoral considerations played no role in October’s decision.
I didn’t hear an utterance about politics. I didn’t hear a reference to politics, elections, what’s happening in the next week or so.
He said of the committee’s two-day meeting.
The political backdrop also includes Trump’s effort to remove Cook from the central bank. Cook, who has challenged that effort in court, has denied the mortgage-fraud allegations cited by the president. Her October dissent favored higher rates, but the published policy statement did not link her vote to that dispute.
Markets still expect another increase
US stocks finished October 28 higher, although they pared some gains after the announcement. Longer-dated Treasury yields extended their rise, while interest-rate futures indicated that traders slightly reduced their expectations for further tightening.
Even after that adjustment, markets were pricing roughly an 80% probability of a rate increase at the Fed’s December 8 to 9 meeting, according to Reuters’ post-meeting report. That was a market-implied expectation, not a commitment from the central bank.
Warsh reinforced that distinction by reiterating his opposition to routinely signaling the future path of policy. “I don’t believe in forward guidance, absent exigent circumstances, absent a crisis,” he said.
For borrowers, the pause offered little immediate relief. CNBC reported that the average 30-year fixed mortgage rate had reached 7.33%, up from 7.12% a month earlier, citing Mortgage News Daily. Mortgage rates track longer-term Treasury yields more closely than the Fed’s overnight policy rate, meaning an unchanged Fed target does not necessarily leave home-financing costs unchanged.
Fewer rate votes, not fewer Fed meetings
Warsh also announced a change to the central bank’s meeting structure. The FOMC will continue to meet eight times a year, but one meeting in 2027 will be devoted exclusively to broad monetary-policy strategy, with neither a rate vote nor a policy statement anticipated. He said he expected two strategy sessions and six policy-setting meetings in 2028.
The distinction matters: the proposal reduces the number of scheduled rate-setting meetings, rather than the total number of committee gatherings. Warsh said the additional strategy time would allow officials to examine longer-term questions alongside their regular assessment of incoming economic data. Details of what the Fed would publish after those strategy sessions remained unresolved.
Before December’s decision, officials will have more evidence on inflation, employment and growth. The immediate tests were the third-quarter gross domestic product report and September PCE inflation figures, both scheduled for October 29. Those releases would help assess whether the stronger economy is compatible with easing price pressures — or whether another rate increase is needed.